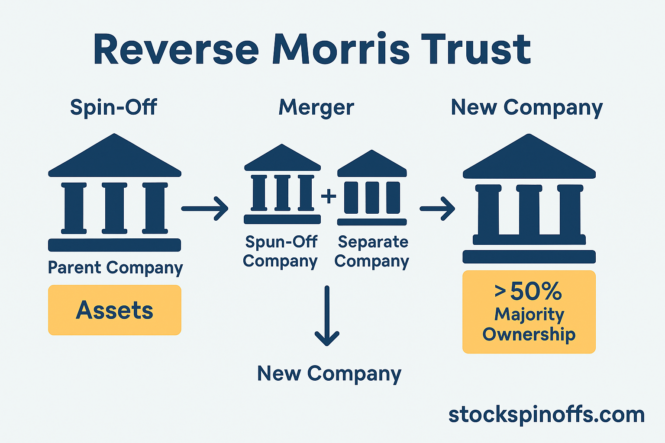
The structure is useful when a division would have a better future as part of another company, but a conventional sale would generate a large tax bill. It can also allow the parent to receive cash as part of the separation. For investors, the important questions are what shares they receive, what debt and cash move between the companies, and how much of the combined business they will own.
How a Reverse Morris Trust works
- Separate the business. The parent transfers the division it wants to divest into a subsidiary, often called SpinCo. The transaction may also allocate debt and other obligations to the subsidiary.
- Distribute the subsidiary. The parent distributes SpinCo shares to its shareholders, typically through a pro rata spinoff or an exchange offer (a split-off). This step is designed to qualify under Section 355 of the Internal Revenue Code.
- Merge with the partner. SpinCo combines with a separate business under a merger intended to qualify as a tax-free reorganization. Shareholders of the former parent end up owning stock in the combined company, alongside the merger partner’s existing shareholders.
In a simplified hypothetical transaction, ParentCo spins off its industrial division and merges it with a publicly traded equipment manufacturer. ParentCo’s shareholders receive 60% of the combined manufacturer, and the manufacturer’s existing shareholders retain 40%. ParentCo no longer operates the division, but its shareholders have an investment in the larger manufacturer.
There is no requirement that the new business trade under the spun-off division’s name or ticker. The spun-off subsidiary may exist only briefly before merging into the partner, and the shares ultimately delivered to shareholders may be those of an already public company. Our earlier Reverse Morris Trust primer explains the name’s origin and some of the older deals that used the structure.
How an RMT differs from an ordinary spinoff or a sale
| Transaction | What happens to the business? | What do parent shareholders receive? |
|---|---|---|
| Ordinary spinoff | Separated business normally becomes an independent company. | Shares in the separated company, while retaining parent shares. |
| Reverse Morris Trust | Separated business merges with another company. | Shares in the combined business; in a pro rata spinoff, they also retain parent shares. |
| Cash sale | Buyer acquires the business for cash or other consideration. | Generally no direct shares in the sold business; proceeds go to the selling company. |
| Classic Morris Trust | The parent, rather than the distributed business, merges with the partner after a spinoff. | Depends on the specific distribution and merger terms. |
The tax difference can be substantial. A parent selling a highly appreciated division may recognize a corporate-level gain, while a properly structured RMT can transfer that business without the same immediate corporate-level tax. A transaction labeled tax-free still requires detailed conditions to be met, and shareholders may owe tax on cash or other elements of the consideration.
An RMT can also move money to the parent. For example, the subsidiary may incur debt and pay a cash distribution to the parent before the merger, subject to the relevant tax and transaction requirements. That can help the parent reduce debt, but it may leave the combined business carrying obligations that investors should examine.
The ownership and tax requirements
The familiar RMT structure is designed around Section 355(e), which can impose corporate-level tax when a spinoff is part of a plan involving the acquisition of a 50% or greater interest in the parent or the distributed company. In a straightforward transaction, the former parent shareholders generally must own more than half of the combined business after the merger, measured under the applicable tax rules. That constraint can limit the size of a suitable merger partner.
The headline share allocation is not always the complete tax calculation. If investors already hold shares in both companies, qualifying overlapping ownership may affect the analysis, as a recent transaction illustrates below. The spinoff, merger, business-purpose, and other requirements still need to be satisfied; passing a single ownership test does not guarantee tax-free treatment.
Three real Reverse Morris Trust examples
Lockheed Martin and Leidos (2016): Lockheed Martin ($LMT) separated its government IT and technical services business and combined it with Leidos ($LDOS) through an RMT. Participating Lockheed shareholders exchanged LMT shares for stock that became Leidos shares, rather than receiving an automatic pro rata distribution. Lockheed received a $1.8 billion cash payment, and the participating holders received approximately 50.5% of the combined Leidos. Lockheed’s closing announcement sets out the transaction’s final mechanics.
GE Transportation and Wabtec (2019): GE ($GE) initially planned a transaction that would have preserved RMT treatment when its transportation business combined with Wabtec ($WAB). The deal was restructured before closing: GE received a larger retained stake, GE shareholders received approximately 24.3% of Wabtec, and the Wabtec distribution was taxable to GE shareholders. GE’s own shareholder tax information describes the resulting Form 1099-DIV treatment. We covered the change in the proposed structure at the time.
Modine and Gentherm (2026): Modine ($MOD) spun off Performance Technologies and combined it with Gentherm ($THRM) on October 1. MOD shareholders kept their MOD stock and received 0.44619 THRM shares for each MOD share held at the record date, with cash paid instead of fractional THRM shares. Modine also received approximately $156 million in cash, used to repay debt. The closing announcement reported that Modine shareholders received 43.62% of Gentherm and pre-transaction Gentherm holders held 56.38%, before accounting for investors who owned both stocks.
Those percentages appear inconsistent with the usual majority-ownership description, but the deal’s SEC prospectus describes an adjustment mechanism that incorporates qualifying overlapping shareholders in the Section 355(e) calculation. Modine obtained a private-letter ruling from the IRS before closing, and the companies described the combination as intended to be tax-free. The 43.62% headline allocation therefore should not be confused with the transaction’s tax-law ownership analysis. Our Modine/Gentherm closing analysis covers the final share ratio and cash consideration in more detail.
What shareholders should check in an announced RMT
First determine whether the distribution will be automatic or will require participation in an exchange offer. In a pro rata spinoff, eligible parent shareholders generally receive shares based on their holdings at the relevant distribution date; in a split-off, participating holders surrender some parent shares in exchange for the separated business. That difference can materially change the size and composition of an investor’s remaining portfolio.
Next read the transaction documents for the exchange or distribution ratio, expected ownership percentages, cash payments to the parent, financing placed on SpinCo, and the division’s valuation. A tax-efficient separation can still be expensive for the combined company if it takes on too much debt or pays too high a price for the business. The merger partner’s existing shareholders also face dilution and integration risks.
Finally, check the stated tax treatment and what could change it. A private-letter ruling applies to the taxpayer and facts addressed in that ruling; it is not a blanket assurance for every investor. Even when the principal distribution is intended to be tax-free, cash in lieu of fractional shares, special payments, and individual tax circumstances can produce different results. Our Upcoming Spinoffs calendar tracks pending distributions and mergers where these terms are still being finalized.
Mentions